Home loans · Snohomish County, WA
Buying a home? Let’s figure it out together.
First home, next home or your equity, explained simply.
Nam Nguyen, Loan Officer, NMLS 2006633 · Dwell Mortgage, LLC, NMLS 2426506 · Equal Housing Opportunity
- Snohomish Countyis my home market, with Everett-based Dwell Mortgage
- Broker, not a bankevery program runs through an approved wholesale lender Dwell has partnered with
- 9 stateswhere Dwell Mortgage, LLC holds a mortgage company licence
The loans I help with most
Each of these has trade-offs, and the right one depends on your income, savings and plans. I’ll walk you through the ones that fit before you commit to anything.
First-time buyers
Down payment assistance, FHA, and conventional options like HomeReady and Home Possible, explained before you start touring so you know what you can afford.
- Down payment assistance programs
- FHA and conventional loans
- Pre-approval before you make an offer
Home equity
Borrow against the home you already own, either as a flexible line of credit or as a fixed second loan that leaves your first mortgage where it is.
- HELOC: a line of credit you draw as needed
- HELOAN: a fixed second mortgage
Refinancing
Replace your current mortgage with a new one to change the term, the payment, or to take cash out. I’ll show you what it costs as well as what it saves.
VA loans
Home loans for eligible veterans, service members and surviving spouses, guaranteed by the U.S. Department of Veterans Affairs.
Jumbo, self-employed and investors
Larger loans, bank-statement and asset-based options for income that does not fit a W-2, and DSCR loans for rental property.
Construction, ADU and renovation
Loans for building a home, adding an accessory dwelling unit, or folding the cost of a renovation into the mortgage.
- New construction
- Accessory dwelling units (ADUs)
- Renovation loans
From the first question to the keys
Four steps, and you will know what happens at each one before it does.
Talk to me
Call or send a message with a sentence about where you are. No forms first. The first conversation is just your questions and straight answers.
Make a plan
We go through your income, savings, credit and the monthly payment you are comfortable with, and I lay the loans that fit side by side.
Get pre-approved and shop
You apply, I review your documents, and you shop with a pre-approval letter behind your offer. Every loan is subject to credit approval.
Close and get the keys
I keep you and your agent updated from accepted offer to closing, so nothing on closing day is a surprise.
About me
Loan officer, fisherman, home cook and gamer
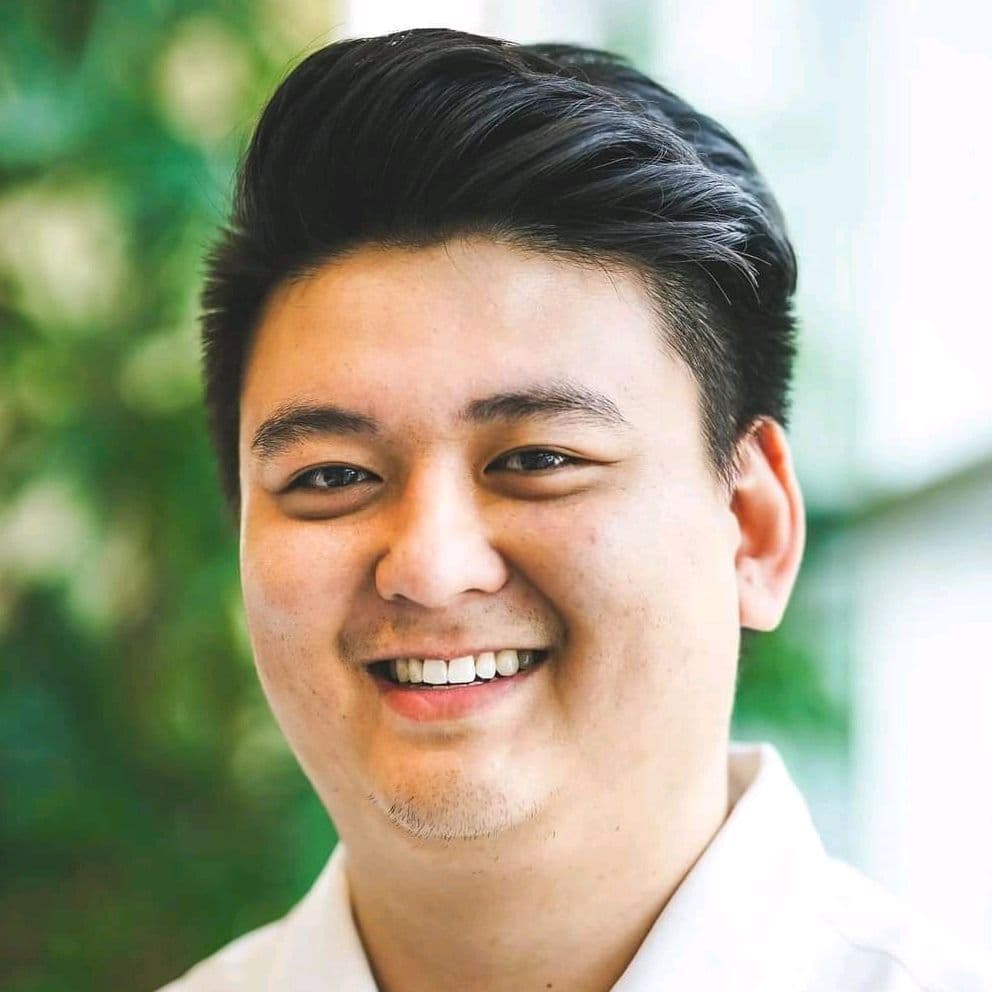
I’m a mortgage loan officer with Dwell Mortgage, a lender headquartered in Everett, and I work with buyers and homeowners around Snohomish County.
A lot of my job is clearing up myths. You don’t always need a huge down payment. Waiting for rates to drop isn’t automatically the smart move. Your credit score is a starting point, not a verdict. I’d rather you understand your options than sign wherever I point.
First home, next home, or pulling equity out of the one you have: I’ll walk you through the numbers, answer the questions you feel silly asking, and keep you and your agent posted until you have keys.
When I’m not working on loans, I’m probably out fishing, cooking something new at home, or gaming.
— Nam Nguyen, Loan Officer, NMLS 2006633
- Loan Officer, NMLS 2006633
- Dwell Mortgage, LLC, NMLS 2426506
- Based in Snohomish County, WA
- Equal Housing Opportunity
The things people ask me first
Do I need a huge down payment to buy a home?
Often, no. Several loan programs are built for buyers with smaller down payments, and down payment assistance programs can help cover it. Putting more down can lower your monthly payment or remove mortgage insurance, but it is not the price of getting started. I’ll show you the options side by side.
Should I wait for rates to drop before I buy?
Nobody can promise where rates go, me included. What we can do is look at what a home would cost you each month today, whether that fits your budget now, and what refinancing later would involve if rates do fall. Waiting has costs too. The decision is yours; my job is to give you honest numbers.
What credit score do I need?
It depends on the loan program, and there is more flexibility than most people expect. Don’t guess, and don’t let it stop you from asking. I can look at where you are now and talk through what would move it.
How does pre-approval work?
You apply, I review your income, assets and credit, and you get a letter showing sellers you are ready to buy. It includes a credit check, and I’ll tell you before anything is pulled. A pre-approval is not a commitment to lend; every loan is subject to credit approval.
Can I use my equity without refinancing my mortgage?
Yes, that is what a HELOC or a home equity loan does. It sits behind your existing mortgage instead of replacing it. Whether it makes sense depends on your equity, your credit and what the money is for.
Who is Dwell Mortgage?
Dwell Mortgage, LLC (NMLS 2426506) is the mortgage company I work with, headquartered on Wetmore Avenue in Everett. Programs are offered through approved wholesale lenders Dwell has partnered with, rather than from one bank’s shelf.
Home loans for Snohomish County.
Just starting to look, or already have a house in mind? Tell me where you are and I’ll tell you straight what your options look like. What happens next is up to you.
Talk to NamAsk me anything about your next move
Call me directly, send a message with the form, or reach me on LinkedIn, Facebook, Instagram or TikTok.
Send me a message
Tell me a little about where you are. A sentence is plenty. Leave an email or a phone number so I can reply.
Availability
- Meetings
- By appointment